Grocery Shopping Habits That Cost More Than Necessary
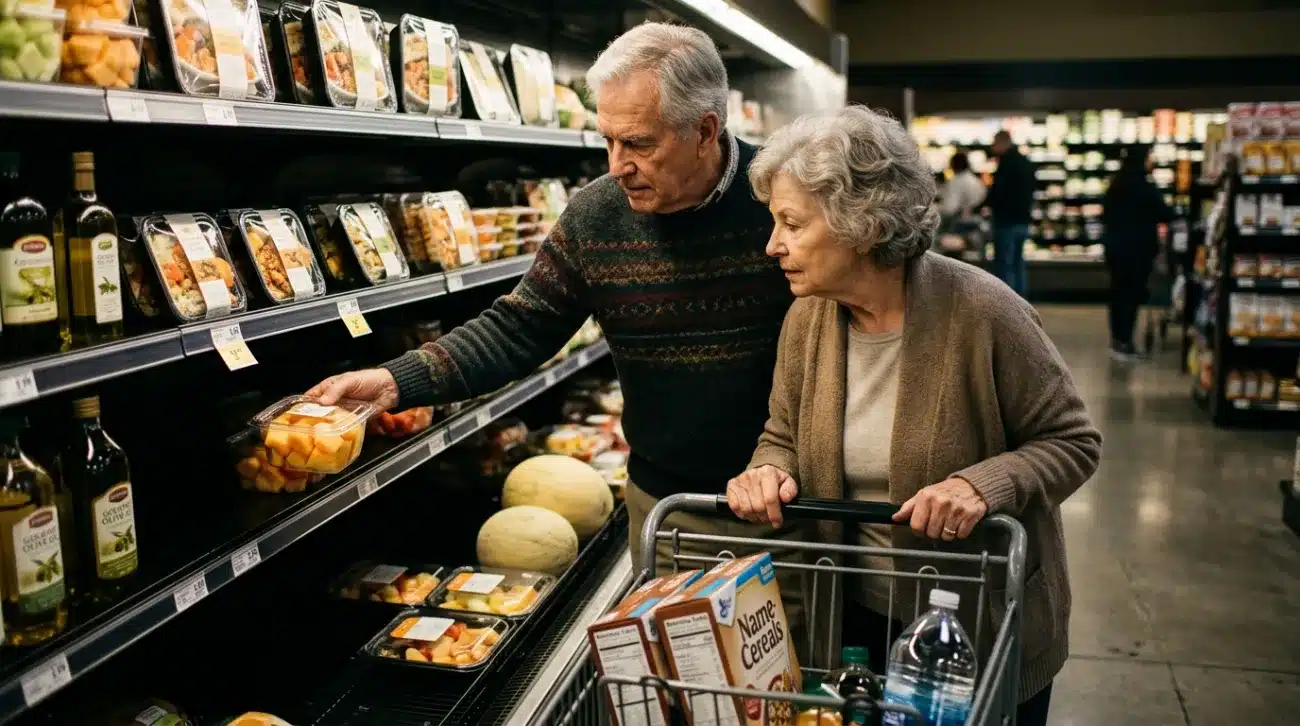
Food represents a necessary expense, but shopping habits developed over decades may no longer serve retirees well. Brand loyalty costs money when store brands and generics offer comparable quality at lower prices. Many major retailers and grocery chains produce their own store-brand products in the same facilities that manufacture name brands, meaning the primary difference is packaging and marketing rather than ingredients or quality.
Shopping patterns also merit examination. Purchasing produce at peak freshness and optimal ripeness from specialty stores costs more than buying from conventional grocers, without necessarily providing better nutrition. Similarly, convenience products like pre-cut vegetables, individual serving packages, and ready-made meals carry substantial premiums over their whole-food equivalents. For retirees with time flexibility, shifting some shopping to senior discount days that many stores offer, or using store loyalty programs strategically, can reduce grocery bills without requiring dietary changes.
Many grocery stores offer senior discount days, typically midweek. Combining these discounts with store loyalty programs and manufacturer coupons for products you already purchase can compound savings without changing what you buy.
Home Maintenance and Service Contracts Worth Reassessing

Home service contracts and extended warranties provide peace of mind, but their value depends entirely on whether the coverage they provide exceeds their cost over time. Many appliance extended warranties and home service agreements cover repairs that rarely occur during the contract period, essentially functioning as insurance policies where the premiums exceed the expected claims. For retirees with some emergency savings, self-insuring against appliance failures by setting aside the money that would otherwise go to warranties may prove more economical.
Similarly, automatic service contracts for HVAC systems, pest control, and lawn care often charge monthly fees that exceed the cost of scheduling services individually on an as-needed basis. While regular maintenance is genuinely important for certain systems, the convenience of automatic scheduling may not justify the premium charged. Comparing the annual cost of service contracts against what individual service calls would cost can clarify whether the contract serves your interests or primarily benefits the provider.
Utility Bills and Energy Efficiency Opportunities

Utility costs represent ongoing expenses that many retirees accept as fixed when they actually offer room for reduction. Many utility providers offer budget billing programs that average annual costs into equal monthly payments, providing predictability but sometimes masking overall increases. Reviewing actual consumption data rather than just payment amounts can reveal trends worth addressing.
Additionally, many utility companies offer free or subsidized energy audits that identify specific opportunities to reduce consumption. From weatherstripping and insulation improvements to programmable thermostats and LED lighting upgrades, efficiency improvements often pay for themselves within a few years through reduced bills. Some utilities also offer time-of-use rate plans that charge less during off-peak hours, which can benefit retirees with schedule flexibility to run dishwashers, laundry, and other appliances during cheaper rate periods.
A Smarter Approach to Managing Retirement Expenses
The expenses retirees pay too much for rarely result from extravagance or carelessness, but rather from inertia and the natural tendency to maintain established patterns. Fixed incomes demand active management precisely because they do not grow to accommodate rising costs. By systematically reviewing each category of regular spending with an eye toward value rather than habit, retirees can often redirect meaningful amounts toward priorities that genuinely enhance their quality of life. The exercise of examining expenses serves another purpose as well, reinforcing a sense of agency and control during a life phase when financial circumstances can otherwise feel constraining. Small savings accumulated across multiple categories compound into significant annual amounts, providing both material benefits and the satisfaction of managing resources wisely. The goal is not deprivation but rather ensuring that every dollar spent delivers proportional value in return.